
Market Observations & Portfolio Commentary
Mid Cap – 3Q2026 vs. Russell Midcap
Market Update
U.S. equities were mixed in the third quarter, with modest index gains but weak participation beneath the surface. The Russell 3000 returned 1.4%, but the average S&P 500 stock declined and Small Caps fell sharply. Strong earnings and improving PMIs supported Large Caps, while the breakdown of U.S.-Iran peace efforts sent oil sharply higher and reignited inflation concerns. The Fed raised rates 25 basis points in September, its first hike since 2023. Treasury yields rose across the curve, with the 10-year at its highest level since 2002. Higher oil and rates compressed valuations and weighed on consumer confidence.
Equity leadership shifted sharply during the quarter. The high-beta and the momentum rally that peaked in late June reversed, and Large Caps were the only size segment to post gains as the Russell 2000 fell 7.2%. Breadth was weak, with the Equal-Weight S&P 500 trailing its cap-weighted counterpart by more than four percentage points. Energy led all sectors as oil surged, and Technology advanced as a software rebound offset weakness in semiconductors. Utilities and Industrials lagged. From a factor perspective, Value, Quality, Size and Yield were all positive. Momentum and Volatility were negative, while Growth factors were mixed.
Key Performance Takeaways
-
The London Company Mid Cap portfolio declined 6.4% (-6.6% net) during the quarter vs. a 3.0% decline in the Russell Midcap Index. Stock selection & sector allocation were headwinds to relative performance.
-
The Mid Cap portfolio trailed the Russell Midcap in a down quarter, falling more than its benchmark and outside our 75–80% downside capture expectations. The quality-led rebound that began in late spring, among the strategy’s strongest relative stretches of the past year, faded through the summer. Underweights to energy and to previously beaten-down software stocks, which carry more weight in the Midcap index, weighed on results. Stock-specific pressure at several consumer-facing and building products holdings added to the shortfall. When quality has been rewarded, the portfolio has performed as designed, and we are finding durable businesses at increasingly attractive valuations.
Top 3 Contributors to Relative Performance
-
Avantor, Inc. (AVTR) – AVTR was a top contributor after results beat expectations and management raised its outlook, with distribution returning to growth. New management is improving productivity and costs, while backlog conversion should support cash flow. We remain encouraged by its improving operations, established life sciences position, and debt reduction.
-
NewMarket Corporation (NEU) – NEU outperformed on solid results, led by strong growth in Specialty Materials serving aerospace and defense. Petroleum additives also improved, while the company reduced debt and repurchased shares. We remain attracted to NEU’s expanding defense capacity, long record of capital returns, and strong cash generation.
-
AppFolio Inc. (APPF) – APPF outperformed after a strong quarter in which customers adopted higher-priced premium tiers that include its new AI agents, and the company raised its revenue outlook. We remain attracted to APPF’s core software platform for property managers, consistent double-digit growth, and ability to expand its AI-driven offerings.
Top 3 Detractors from Relative Performance
-
Lennox International (LII) – LII declined after softer residential volumes and lower guidance, driven largely by weak new construction and delayed pricing. Commercial trends remained strong, and management sees residential demand nearing a bottom. We continue to like LII’s replacement-driven HVAC exposure, strong balance sheet, and long-term earnings potential.
-
Somnigroup International Inc. (SGI) – SGI declined as weak mattress demand pushed out the industry recovery and led management to lower its outlook. Despite the softer backdrop, the company continued to gain share, expand margins, exceed Mattress Firm synergy targets, and complete the Leggett & Platt acquisition, which adds further self-help opportunities. We remain confident that its scale, vertical integration, cash generation, and synergy potential position it well as industry conditions normalize.
-
Entegris, Inc. (ENTG) – ENTG declined as semiconductor stocks pulled back after a very large run, despite a strong quarter with accelerating customer spending. We remain attracted to ENTG’s competitive position, high barriers to entry, and rising free cash flow as its investment cycle winds down.
Sector Influence
We are bottom-up stock pickers, but sector exposures influenced relative performance as follows:
-
What Helped: Underweight Utilities (a weaker performing sector) & overweight Health Care (a better performing sector)
-
What Hurt: Underweight Energy (a better performing sector) & overweight Industrials (a weaker performing sector)
Trades During the Quarter
-
Initiated & Increased: Verisk Analytics, Inc. (VRSK) – VRSK provides data, analytics, and software to the U.S. property and casualty insurance industry. Nearly every major insurer relies on its tools to price policies and process claims, and its hard-to-replicate proprietary data should become more valuable as insurers adopt artificial intelligence. Subscription revenue and high retention support steady growth and pricing power, with high profitability and modest capital needs. Management has sharpened its insurance focus, ties pay to returns on capital, and deploys excess cash toward small acquisitions, buybacks, and a growing dividend. A recent pullback let us own this high-quality business at a reasonable price.
-
Reduced: Entegris, Inc. (ENTG) – Trimmed after strong performance; our long-term thesis remains intact.
-
Reduced: UniFirst Corporation (UNF) – Trimmed with shares near the announced Cintas (CTAS) deal price; proceeds funded our VRSK addition.
-
Initiated: Honeywell Aerospace Inc. (HONA) – HONA supplies commercial aviation, business jet, and defense customers and became independent through its June spin-off from Honeywell. Its products are on most aircraft flying today. Because planes stay in service for decades, each original sale generates years of higher-margin parts and service revenue, which makes up most of its sales. Long development cycles and strict regulation create high barriers to entry. We expect HONA to benefit from growing air travel, rising defense spending, and limited industry capacity. Despite potentially uneven near-term results, we believe its durable advantages make it an attractive long-term investment.
-
Initiated: TE Connectivity Ltd. (TEL) – TEL makes the connectors and sensors that carry power and data inside cars, factory equipment, and increasingly AI-driven data centers. As these products become more electrified and connected, they require more of TEL’s components, allowing the company to outgrow its end markets over time. Industrial demand remains solid, and automotive gains continue despite softer vehicle production. Strong cash flow and a solid balance sheet support consistent shareholder returns. Recent margin and growth improvement increases our confidence in an outlook we believe the valuation does not fully reflect.
-
Increased: CBRE Group, Inc. (CBRE) – Added on this year’s pullback. Leasing is improving, facilities management remains steady, and data centers offer growth across both construction and ongoing management. We believe the valuation does not fully reflect this.
-
Exited: Bruker Corporation (BRKR) – Sold the small position after a rally. We retain exposure through our SMID portfolio and our larger Waters Corporation (WAT) weighting.
-
Exited: Copart, Inc. (CPRT) – Sold the small position after more than a decade of ownership, given execution risk in its whole-car market expansion.
-
Exited: Pool Corporation (POOL) – Sold given a muted earnings outlook, with few catalysts until new pool construction recovers.
Looking Ahead
The economic backdrop remains supportive, with solid growth, improving manufacturing and services activity, and earnings that continue to exceed elevated expectations. At the same time, headwinds have grown more pronounced. The Fed has begun tightening, energy prices and Treasury yields are elevated, and higher costs are weighing on consumers. The AI investment cycle remains a powerful growth engine, but its scale invites comparisons to past infrastructure booms, and early signs of stress have emerged in the lowest tiers of credit. We believe these crosscurrents argue for discipline.
Headline index strength masks a narrower reality, as a concentrated group of AI-linked companies has driven a disproportionate share of returns. Quality has historically lagged when rates rise, but if higher rates begin to pressure balance sheets, the attributes we emphasize should matter more: strong returns on capital, conservative leverage, durable dividends, and reasonable valuations. We remain confident that our portfolios are well positioned to participate as fundamentals reassert themselves while helping to manage downside risk.
Annualized Returns
As of 9/30/2026
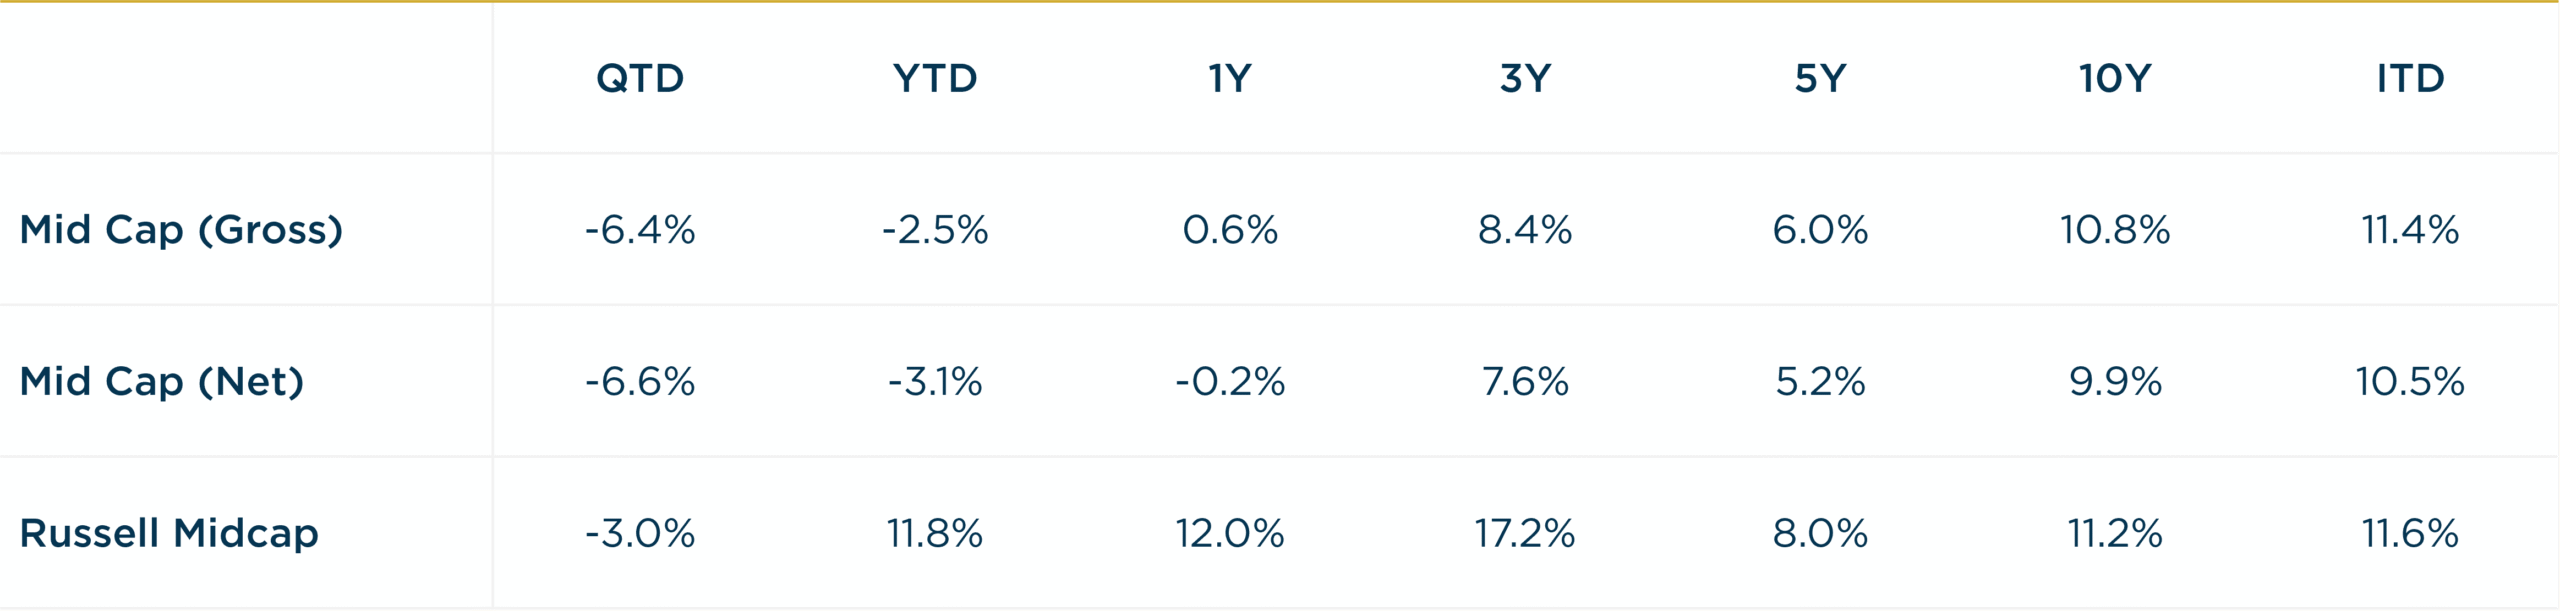
Inception date: 3/31/2012. Performance is preliminary. Subject to change. Past performance should not be taken as a guarantee of future results. Net of fee returns are calculated net of an annual model management fee of 0.75%. Please see the disclosure notes found on the bottom of the page.